
Globalisation Achilles Heel
As the world continues its march towards ‘normalisation’, worldwide logistics are still struggling. Today we unveil the key logistical weak points of Stake’s customer and investment markets: Australia, New Zealand and the U.S.
Globalisation. Some say it’s in retreat and some believe it’s as strong as ever. But one thing everybody can agree on is the engine that’s driven it to its current heights: trade. However, as we’ve seen over the COVID-19 era, the system of global trade is incredibly fragile, with many weak points. Let’s take a look.
High Demand For Low Emissions
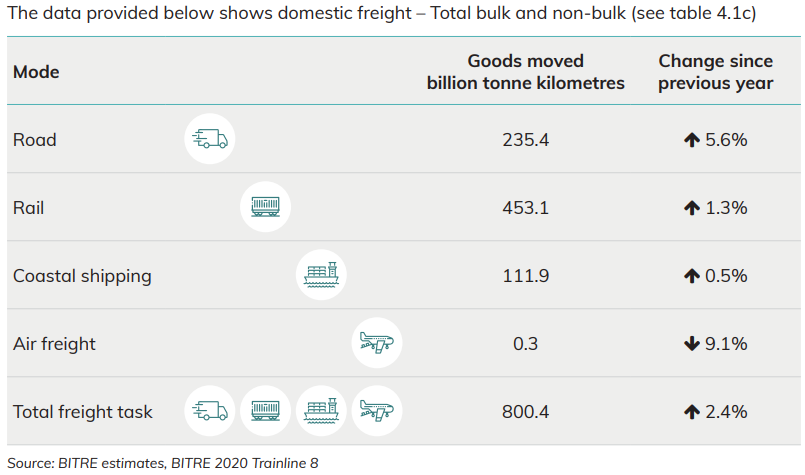
For an island surrounded by water, Australia’s logistics rely far more on roads and rails than coastal shipping. According to the Australian Government’s annual Australian Infrastructure and Transport Statistics, in 2021, 795b tonne kilometres (tkm – a freight transport term that equates to one tonne transported over one kilometre) of domestic freight were moved across the country. Roads not only were the second largest source of freight movement, but also experienced the largest year-on-year growth in tkm.
When it comes to Australian domestic road freight, the vast majority is transported by diesel trucks. Diesel trucks require a wide range of products to operate, but not many people would think of the anti-pollutant AdBlue. AdBlue is a mixture of an organic compound called urea and deionised water, and it’s injected into the exhaust system to turn nitrogen oxides into nitrogen and water before leaving the vehicle.
In a logistical problem that might have troubled Australia regardless of COVID-19, AdBlue demand has skyrocketed recently as there are few alternatives, and emission standards have been on the rise. Putting additional pressure on the situation is the rising cost of fertiliser in China, causing the government to put restrictions on urea exports. Unfortunately for Australia, 80% of its urea supplies come from China, the world’s largest producer. No urea, no AdBlue.
If you think the situation can be resolved by temporarily reducing emission standards, think again. Due to their construction, diesel trucks and cars that use AdBlue cannot run without it, according to insurer AA. Supplies continue to be restricted in Australia, and will likely be for some time, but good news came on 24 January 2022, when 3m litres of AdBlue were produced in Australia over a week for the first time. Still, without a long-term strategy, freight-related companies and investments will have to deal with uncertainty for a while.
Missing Foundations
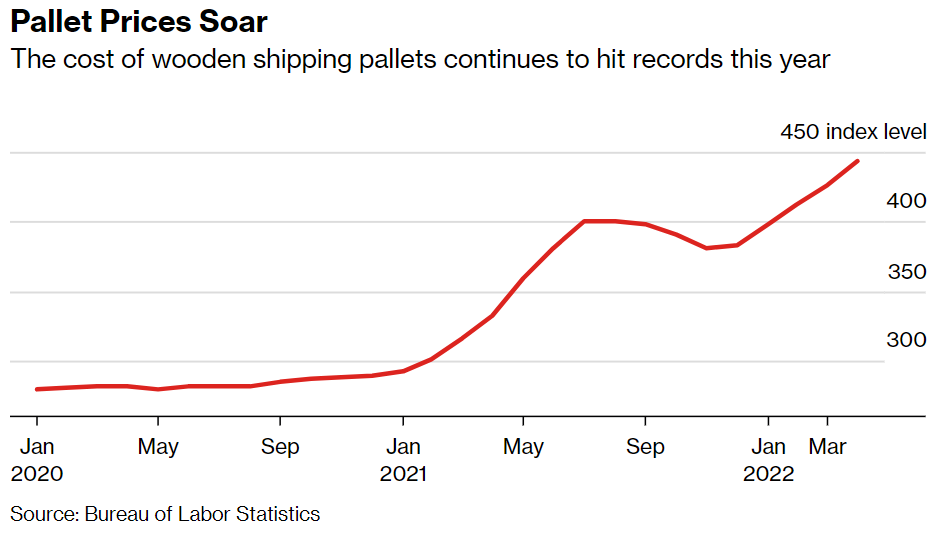
Since COVID-19 and the logistics crisis began in the U.S., one issue has been clogging up the system from day one. The shortage of shipping pallets. The reason for the shortage is the circular economy, or how it’s been disrupted. Technically there’s always been a shortage of pallets, but with shipments coming and going, things sorted themselves out. It only really became a problem when freight started to sit for long periods of time.
While the situation has improved in the U.S. in 2022, it’s far from resolved, as illustrated by the chart below from Bloomberg:
A Lack Of Capacity
New Zealand’s distance from other countries has long been a double-edged sword. While it arguably has helped the country fend off the coronavirus very well, it’s been mainly a hindrance when it comes to COVID-19 logistics. According to the 2021 ExportNZ DHL Barometer, ‘shipping and logistics’ was the number one issue for Kiwi exporters.
BusinessNZ believes the main reason behind New Zealand’s current logistical issues (besides the global crisis) is a lack of investment in the domestic supply chain, leading to capacity issues. Fortunately, the New Zealand government is aware of the problem, and is developing a freight and supply chain strategy to help inform investment decisions.
To be clear, formulating a strategy is far from investing in the problem, but even fixing the need for investment in the domestic supply chain won’t fix the global supply chain.
No One In The Driver’s Seat
While job shortages are nothing new in the COVID-19 era, the UK has been hit especially hard. One of the main areas hit by the lack of specialised labour has been heavy goods vehicle (HGV) drivers. According to a report by Logistics UK released in December 2021, the availability of HGV drivers dropped 24% compared to 2019.
While the UK has seen a 3x increase in applications for vocational provisional licences, Logistics UK attributes this mainly to the 10% rise in pay during 2021. So, while the problem seems to be improving, it’s mostly dependent on increasing costs. This may not be so bad considering the UK sits towards the lower end of the payscale for HGV drivers: £30,000 compared to €41,000 in Germany.
Shipping Costs Its Weight In Gold
In 2020, China was the main consumer of Brazil’s exports, spending US$67.9b according to the Observatory of Economic Complexity (OEC). That trade route is now under pressure due to a dramatic increase in costs. How dramatic? Prior to the pandemic, a 40-foot reefer container in the short-term market cost between US$3,000 and US$4,000 for the route between Brazil and Asia. As of April 2022, as shown in a survey by the National Confederation of Industry (CNI), that cost reached US$6,800 – a 58% year-on-year increase. Recent lockdowns in China and continued logistical pressure in Asia means prices will likely continue to rise.
While many countries continue to have problems with logistics, the good news is that the situation is improving – for the most part. We’re probably a few years away from solving the global supply chain crisis, but there are always opportunities in the market for those willing to do their own research.
Subscribe
By subscribing, you agree to our Privacy Policy.